Sky Dancing

a place to discuss real issues

  • Disequilibrium is an interesting concept that has roots in many disciplines. Of course, in physiology it just simply means something’s off balance. You can have an inner ear infection, become dizzy, and feel miserable as well as fall because you become unsteady on your feet. That’s the kind of disequilibrium associated with vertigo. There’s linkage disequilibrium which is a term used in population genetics which causes diseases like cystic fibrosis when there are “non-random association of alleles at two or more loci, not necessarily on the same chromosome.” Something’s off balance there too, although I frankly can’t explain it at all.

    In economics, disequilibrium is a state where a market can’t achieve that place where forces reach a state of balance in terms of supply and demand. You don’t achieve the magical market clearing status called equilibrium where you get this mutually agreed upon price level and quantity so things usually stay at a place where you get excesses or shortages and the society really wastes a lot of communal resources. Wasting resources is a big welfare inhibitor in this situation because you’re preventing a state where a lot more mutually beneficial transactions could occur. We’re looking for optimality, for efficiency, for correct allocation of resources and none will happen.

    I’m not a psychologist but I’ve had more than a few psychology courses and I do love the idea of disequilibrium in this discipline. I studied cognitive dissonance a lot when I got a teaching certificate and had to endure quite a few hours in educational psychology and psychology. You just can’t avoid the work of Jean Piaget and disequilibrium in cognitive development. It is one of his big things. I was so impressed with his work that both my children went to Montessori schools which is an offshoot of his studies on human development. You can ask BostonBoomer the details because that’s her thing, not mine. Mine is General Equilibrium of the economic sort but it operates in markets instead of the minds of children.
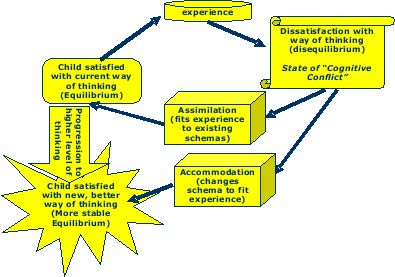
    I’ve put the nifty graphic in there which shows you the basic Piaget model. In all the processes of disequilibrium, the cognitive one included, something is off-balance. It just isn’t right. When you get a sense of cognitive dissonance your supposed to get an uncomfortable feeling because you’re holding two logically inconsistent viewpoints in your mind and it upsets your balance. That’s the state of Cognitive Conflict. You react noticeably as you try to reconcile the two distinct beliefs or states. In psychology this can lead to what they call confirmation bias where your mind starts blocking out evidence so that you can feel better about the situation by ignoring the disconfirming evidence altogether. It’s basically an ego defense mechanism.

    So, back to economics now where our model is out of whack because something is in the way of the market reaching equilibrium. Either supply or demand has been fettered by something. This something can come from the government in the form of quotas, tariffs or price controls. It also can come from the market. Something can slow the process to equilibrium like “sticky downward’ or rigid wages which is a Keynesian concept related to people not particularly liking their incomes and budgets messed with regardless of what’s going on with prices in the broader economy. This is a economics example of cognitive dissonance, although most economists will completely run the other way whenever you try to equate their sacred science with something that resembles ‘psycho-babble’ and not their model of the rational, need driven householder.

    So, why am I babbling on about this like the weird and wonky academic with a lot of background in social science research that I have? Because, I sense a huge macro-disequilibrium in the United States right now in a much more multi-discliplined way than most social scientists or scientists sense and study.

    Something doesn’t feel right and I can’t solve the equation. It’s a disequilibrium in that touch- feely cognitive dissonance sort’ve way that I believe is coming from one of the root sources of economic disequilibrium. That would be perverse incentives. The government can put a market perpetually out of equilibrium by taxing or rewarding behaviors that make one side benefit and the other side lose. This is what happens when they use Tobin Taxes (so-called sin taxes) or quotas for imports or quantity restrictions to prop up businesses, or some other kind of price controls. The result is measurable in a market. It creates what we call a deadweight loss. This is a situation where there is no Pareto optimality, ever, which is that state of equilibrium where supply equals demand, the right price is achieved and an optimum quantity becomes available to the market. Deadweight loss is an excess burden which reflects the loss to society of not having the Pareto or optimal outcome. We lose something. We transfer benefit from one group to another or from both groups to the government for one reason or another. Sometimes, we do this for seemingly quite good and innocuous reasons, but it still creates disequilibrium. Usually, it’s perverse incentives. We try to correct some problem and just wind up creating a bigger problem, like New York City did with Rent Controls in the 1970s.

    What’s been going on recently is just one set of circumstances that’s throwing off the balance of one thing after another and it’s transferring the benefit from one group to another. It’s like some perverse set of incentives is causing us to self-destruct in a way that makes us all feel this massive group cognitive dissonance. Something just doesn’t feel right and we can’t use the evidence that exists to find equilibrium because we can’t get there from here without throwing out some of the evidence just to get rid of that off feeling.

    So, the deal is, in Psychology, some people are able to throw out evidence. They will convince themselves that up is down and right is wrong to maintain a sense of equilibrium even when evidence suggests equilibrium cannot be achieved under this conflicting evidence or under these perverse incentives. That, for all the good that it does, explains why some folks can believe that this mess of a health policy will solve ills and achieve goals when it is likely to create a massive wealth transfer and a huge deadweight loss to society. It makes them feel better to believe that this is a circumstance where the lightbringer will deliver their pony. It justifies their decision to support him at all costs. Others, will go batshit crazy and vote Republican. It completely depends on which evidence you throw out. Some of us will just sit here trying to resolve our sense of unease unsuccessfully.

    I’ve never been very good at inducing a state of denial, and I assume that most of you here aren’t either, so where does it leave us?

    My answer is simply in that we are in state of cognitive vertigo together. Maybe, at the moment, that’s the best we can do.
  • The European Union appears to be serious about stopping the hedge fund casino where you get to bet on the failure of countries to meet their sovereign debt obligations with other folks’ money. It also wants to increase regulation that provides more transparency which should–theoretically–lead to increased protection from moral hazard and insiders with inside information acting against the best interests of other investors. Would you consider this action to be protectionist? (i.e. against free trade agreements?) Once again, I’m turning to the UK’s Financial Times for more information.

    Evidently, Timothy Geithner our Secretary of Treasury Goldman’s Sachs Financial Interests is arguing just that.

    Tim Geithner, US Treasury secretary, has delivered a blunt warning to the European Commission that its plans to regulate the hedge fund and private equity industries could cause a transatlantic rift by discriminating against US groups.

    A letter sent by Mr Geithner this month to Michel Barnier, Europe’s internal market commissioner, makes it clear that the European Union is heading for a clash with Washington if it pushes ahead with what the US – and Britain – fear could be a protectionist law.

    As we see the continual watering-down of financial regulation met to rein in the worst of credit abuses in the country, we now see our government arguing against reining-in the casino-style side bets of the hedge funds. The UK is raging against the reform machine too.

    The draft EU directive would impose tighter restrictions on hedge funds, private equity and other alternative investment funds. It has caused alarm in the City of London, where some in the industry say it is a thinly veiled attempt by France and Germany to undermine the UK’s dominance of financial services.

    Okay, so this is my question. How is this going to undermine the dominance of the UK and US investment houses? How does this stop them from competing for business? The answer is in one clause that may or may not be the real issue here.

    Mr Geithner warns that US hedge funds, private equity groups and banks could be discriminated against if proposals to restrict the access of EU investors to funds based outside the 27-country bloc are included in the final law.

    So-called “third country” elements of the directive would force non-EU funds to comply with the new rules if they wish to market themselves at all within the EU. The directive could also force EU-based private equity and hedge funds to use only locally based banks as custodians and depositaries.

    Contentious areas also include rules on remuneration, limits on borrowing, the disclosure of sensitive information and the regime for depositaries.

    Paul Myners, UK financial services minister, told a meeting of private equity executives on Wednesday that he would fight “line by line and minute by minute” to defend the free movement of capital. But he also warned that “nobody in this room is going to get the directive they want”.

    One senior private equity executive said the UK needed to take a stand before others would rally behind it.

    I can see how portions could restrict the movement of capital from one country to another if investors are forced to use local banks. However, asking the UK and US hedge funds to comply with the EU rules doesn’t seem any different than asking FORD or GM to comply with the tougher MPG or emissions standards by the EU or for that matter asking US food companies to restrict certain ingredients either. Most other U.S. industries comply with EU rules daily. One major example is the use of the metric system. So, why can’t Goldman Sachs and JP Morgan just shut up and comply?

    Here’s what is more likely at the heart of the argument.

    One regulation they do not want is one that bans speculative trading on naked CDS.

    The momentum for a ban on naked CDS is getting stronger. Germany and France on Wednesday called on the European Union to consider banning speculative trading in credit default swaps and set up a compulsory register of derivatives trading, the FT reports. Angela Merkel and Francois Fillon sent a letter to Jose Barroso yesterday, asking for an immediate investigation of the role and effect of speculative trading in CDSs in the sovereign bonds of European Union member states. Fillon assured after talks in Berlin, that both governments are “very much in agreement in tackling extreme speculation”.

    Earlier this week, Mario Draghi indicated that tighter regulation of CDS could become a G20 issue when he confirmed that the subject will be on the agenda of the Financial Stability Board (FSB), Reuters reports.

    Four EU member states have called for an investigation into the role of these things in Greece’s problems.

    An inquiry must be opened into the role and impact of speculation linked to credit default swaps trading in EU government bonds as soon as possible to determine any market abuse, the heads of four countries said.

    The move stops short of repeating recent calls for an immediate ban on selling CDS contracts to ‘naked’ buyers who have no interest in the underlying asset — thereby making it easier to find broad backing from the bloc’s finance ministers who will discuss CDS markets next Tuesday.

    In a joint letter to European Commission President Jose Manuel Barroso and Spanish Prime Minister Jose Luis Rodriguez Zapatero, dated March 10, Germany, Luxembourg, France and Greece also called for more transparency on derivative markets.

    The moves would be aimed at preventing undue speculation, enhancing transparency and improving the safety of derivative transactions, according to the letter, which was released by the office of French President Nicolas Sarkozy on Thursday.

    So is Geithner complaining about the provision to restrict business in certain countries to local banks or the restrictions on some of the more exotic and toxic financial innovations? That would include the ones that have troubled both Greece and Iceland.

    Meanwhile, Bloomberg reports that Senator Future Lobbyist of America member Chris Dodd is about ready to unveil his version of Financial Reform. This reflects his compromise with Republican committee member Bob Corker. Have I mentioned recently that nothing particularly good ever comes from compromising with a right wing nut? Oh, yes, that would be yesterday’s post where we talked about Corker’s goal of exempting payday lenders from regulation meant to stop lending abuse. Still, let’s go to Bloomberg for the latest controversy in OUR financial industry reform.

    The new Dodd bill will include some elements negotiated with Corker. For example, it won’t propose the stand-alone agency, which Corker opposed, and will probably put the consumer unit in the Federal Reserve with an independent budget, a director appointed by the president and some enforcement powers, according to a person with direct knowledge of the plan.

    “It has always been my goal to produce a consensus package,” Dodd said in the statement. “And we have reached a point where bringing the bill to the full committee is the best course of action to achieve that end.”

    Notice the difference in the content between the EU talks and the US version. The EU is talking about serious regulation and the US is creating another level of bureaucracy within the FED with “some enforcement powers”. This is like trying to protect some one from AIDS by handing them a virginity pledge to sign when they ain’t no virgin.

    It has to be the power of the FIRE lobby. All you have to do is read any of the academic literature on the financial industry to know that standardization of process and translucency, along with making investors have skin in their game creates stronger and deeper financial markets. While we are shuffling decks on the Titanic, the Europeans are looking at the engines. I just wish I had more control over my pension plan (which unfortunately has to be a selection of professionally ‘managed’ screwed up funds rather than letting me have my own money to invest as I see fit.

    Who is going to stop Wall Street before they kill again?

  • If you want a good example of politics-as-usual as well as something that is not in the interest of the public, this is it. Payday lenders are loan sharks without the kneecapping thugs. Senator Bob Corker wants them exempted from regulations aimed at protecting consumers from predatory and unfair lending practices. Senator Chris Dodd is basically going along with it. This is an egregious example of crony capitalism that enriches an industry by taking advantage of the poor and uninformed.

    Senator Bob Corker, the Tennessee Republican who is playing a crucial role in bipartisan negotiations over financial regulation, pressed to remove a provision from draft legislation that would have empowered federal authorities to crack down on payday lenders, people involved in the talks said. The industry is politically influential in his home state and a significant contributor to his campaigns, records show.

    This is really bad. If you have a congress critter sitting on Dodd’s committee, now is the time to write and scream. Here’s information on from the Center for Responsible Lending on just exactly how bad this particular brand of predators can get.

    Twenty or so years ago, some finance companies figured out how to make loans of a few hundred dollars to people who were barely getting by. That may sound generous, but when you look deeper, the practice they developed amounts to nothing more than legal loan sharking.

    The problem for the borrowers—and the payoff for the lenders—is that the terms of these loans are cleverly designed to be very difficult to meet. The borrower must keep coming back and renewing their loan because they aren’t allowed to pay it down and can’t afford to pay it off. They pay the lender another chunk of interest each time, about $50 for a $300 loan. How the debt trap works

    These loans carry annual interest rates of 400%, and the industry relies for 90 percent of their revenue on borrowers who repeatedly renew or re-open their payday loans. The typical borrower ends up paying about $500 in interest for a $300 loan, and still owes the principal.

    Corker has already damaged the bill that was designed to stop a repeat of the subprime lending crisis that triggered so much trouble back in 2007. Dodd is going along with everything like the lobbyist he surely will become in a short amount of time. We’ve already seen the take down of the new consumer agency that was originally created by the bill. The duties will now be given to the Fed. This is something that Fed Chair Ben Bernanke originally opposed but later accepted under duress from Treasury Secretary Timothy Geithner.

    The Fed is a conservative organization that is more reactive than proactive. Under this new term, it is unlikely any one will activate regulation for this set of loans should they get any worse than they already are today. This basically ghettos the poorest of the poor (mostly the unbanked who rely heavily on checking cashing places and pay day loans) into the least controlled debt instruments. In other words, it’s going to take the most money and fees from those least able to pay for them. It perpetuates the loan trap. Most of the brick and mortar of the pay day loan industry is located in the poorest parts of cities where no bank will go any more. The industry says that it’s providing a much needed service. What’s really happening is that it’s ensuring there is no place else to go.

    Under the proposal agreed to by Mr. Dodd and Mr. Corker, the new consumer agency could write rules for nonbank financial companies like payday lenders. It could enforce such rules against nonbank mortgage companies, mainly loan originators or servicers, but it would have to petition a body of regulators for authority over payday lenders and other nonbank financial companies.
    Consumer advocates said that writing rules without the inherent power to enforce them would leave the agency toothless.

    The consumer groups that seek to protect borrowers from the worst of abuses appear to have given up on Dodd and his committee. They’ve gone straight to the FED for help. The hope is that Bernanke can convince the committee to give the FED broader powers than just ensuring compliance with the Truth in Lending Act.

    Consumer groups, however, say that enforcement is crucial to curbing abusive, deceptive or unfair practices.
    On Tuesday, while Mr. Dodd and Mr. Corker continued negotiating other provisions of the regulatory overhaul — notably, the extent to which state attorneys general would be able to enforce consumer protection rules against banks — the Federal Reserve’s chairman, Ben S. Bernanke, met with National People’s Action, an activist group that wants the Fed to restrict the banks it oversees from financing payday lenders.
    Mr. Bernanke, who had met with the group twice before, is trying to fend off proposals in the Senate to strip the Fed of much of its power to supervise banks. A recommitment to protection consumers is part of that strategy

    It is just unbelievable to me that some of the very people who nearly brought the economy to the knees by taking on unbelievable risks, securitizing them and then passing the trash to the market will still be able to carry on like nothing ever happened. This is terrible news. The only hope now is that Barney Frank will stop the senate from changing the tougher language originally introduced by the White House and put through by the House. It certainly doesn’t look like the White House will stand up for its own bill.

  • Perspective

    The WSJ has an interesting list of folks contributing to “Academics on What Caused the Financial Crisis“. You’ll find a lot of the usual suspects that we’ve talked about around here. There’s some interesting comments on the housing and subprime bubbles, the increased use of exotic financial instruments, and our old friend moral hazard. I’m going to a highlight just a few for you.

    Some of the more interesting comments focused on how the housing bubble was enabled by government. Some blame low interest rates by the FED, others see that it wasn’t just a U.S. phenomenon and look for bigger reasons. Many folks see securitization and the pass-the-trash loan model as the big factors.

    Dwight Jaffee, Haas School of Business, University of California at Berkeley

    On the government’s role in creating the housing bubble: “I find the GSEs [government sponsored enterprises including Freddie Mac and Fannie Mae] to have been a significant factor in expanding the mortgage crisis as a result of their high volume of high-risk mortgage purchases and guarantees. Furthermore, I find that the GSE housing goals for lending to lower-income households and in lower-income regions were secondary to profits as a factor motivating the GSE investments in high-risk mortgages.

    …

    Christopher Mayer, Columbia Business School

    On the housing bubble: “For the housing market, the picture is much more complex than it might first appear. The housing bubble was global in nature and also included commercial real estate, so simple explanations that rely solely on predominantly American institutions like subprime lending or highly structured securitizations cannot be the only factor leading to real estate market excesses. …My own research shows the important role played by declining long‐term, real interest rates in helping drive real estate prices to high levels, at least up to 2005. However, at some point, speculation by both borrowers and lenders took over, leading to excessive appreciation in many parts of the United States and the rest of the world.”

    …

    Pierre-Olivier Gourinchas, University of California at Berkeley:

    How did subprime bust trigger a financial tsunami? “Three factors ensured that the collapse in what was a minor segment of the U.S. financial markets turned into a global financial conflagration. First, profound structural changes in the banking system, with the emergence of the ‘originate-and-distribute’ model, coupled with an increased securitization of credit instruments, led to a decline in lending standards and a general inability to re-price complex financial products when liquidity dried-up.

    Randall Kroszner, University of Chicago Booth School of Business and a former Fed governor:

    On reducing moral hazard: “Given the extent of interventions world-wide, issues of moral hazard will remain. The Rubicon cannot be uncrossed and financial market behavior will surely anticipate the return of the “temporary” programs and guarantees in the event of another crisis. To maintain the stability of the system and to protect taxpayers, the “too interconnected to fail” problem needs to be addressed in two ways: through improvements in the supervision and regulation framework as well as improvements in the legal and market infrastructure to make markets more robust globally.”

    “Ultimately, to mitigate the potential for moral hazard, policy makers must feel that the markets are sufficiently robust that institutions can be allowed to fail with extremely low likelihood of dire consequences for the system.”

    These are just a few brief excerpts from a few of the contributors. You should really go check out the full article.

    In the same vein, I wanted once again to go behind the unemployment number released to day and the WSJ has a pretty good explanation of the figure that I follow closely. It is called the U-6 unemployment rate. It not only focuses on people without jobs but people that are ‘underemployed’. This rate, unlike the unemployment rate itself which is staying around 9.7%, went up last month.

    The U.S. jobless rate was unchanged at 9.7% in February, following a decline the previous month, but the government’s broader measure of unemployment ticked up 0.3 percentage point to 16.8%.

    The comprehensive gauge of labor underutilization, known as the “U-6″ for its data classification by the Labor Department, accounts for people who have stopped looking for work or who can’t find full-time jobs. Though the rate is still 0.6 percentage point below its high of 17.4% in October, its continuing divergence from the official number (the “U-3″ unemployment measure) indicates the job market has a long way to go before growth in the economy translates into relief for workers.

    You can read more at NYT in a thread called “Is the Recovery Losing Steam?”

    Again and despite what AZ Senator John Kyle says–as highlighted in Krugman’s recent op-ed “Bunning’s Universe”–most folks cannot make ends meet on unemployment benefits and must find jobs that are way beneath their job skills, their income requirements, or the lower the number of hours they wish to work. This more realistic rate accounts also for people who simply have given up on finding a job. These folks don’t even collect unemployment benefits. Just to remind you on Kyle’s priorities, here’s a good bit of prose from Krugman.

    Consider, in particular, the position that Mr. Kyl has taken on a proposed bill that would extend unemployment benefits and health insurance subsidies for the jobless for the rest of the year. Republicans will block that bill, said Mr. Kyl, unless they get a “path forward fairly soon” on the estate tax.

    Now, the House has already passed a bill that, by exempting the assets of couples up to $7 million, would leave 99.75 percent of estates tax-free. But that doesn’t seem to be enough for Mr. Kyl; he’s willing to hold up desperately needed aid to the unemployed on behalf of the remaining 0.25 percent. That’s a very clear statement of priorities.

    You can see from various folks quoted on top (some from liberal and some from staunchly conservative b-schools), they do not place the blame for the last financial catastrophe on folks who don’t want to work and simply want to sit around collecting government money. Yet, if you look at today’s unemployment numbers, it’s just plain working folks that are not recovering from the financial global crisis. They are not getting the policy or money to deal with what the crisis did to them. Instead, the people who cause it are the one’s getting giant bonuses, boosts in stock prices, and continued government goodies.

    Life isn’t necessarily fair, but does macroeconomic policy have to be so too during a Democratically led Congress and White House?